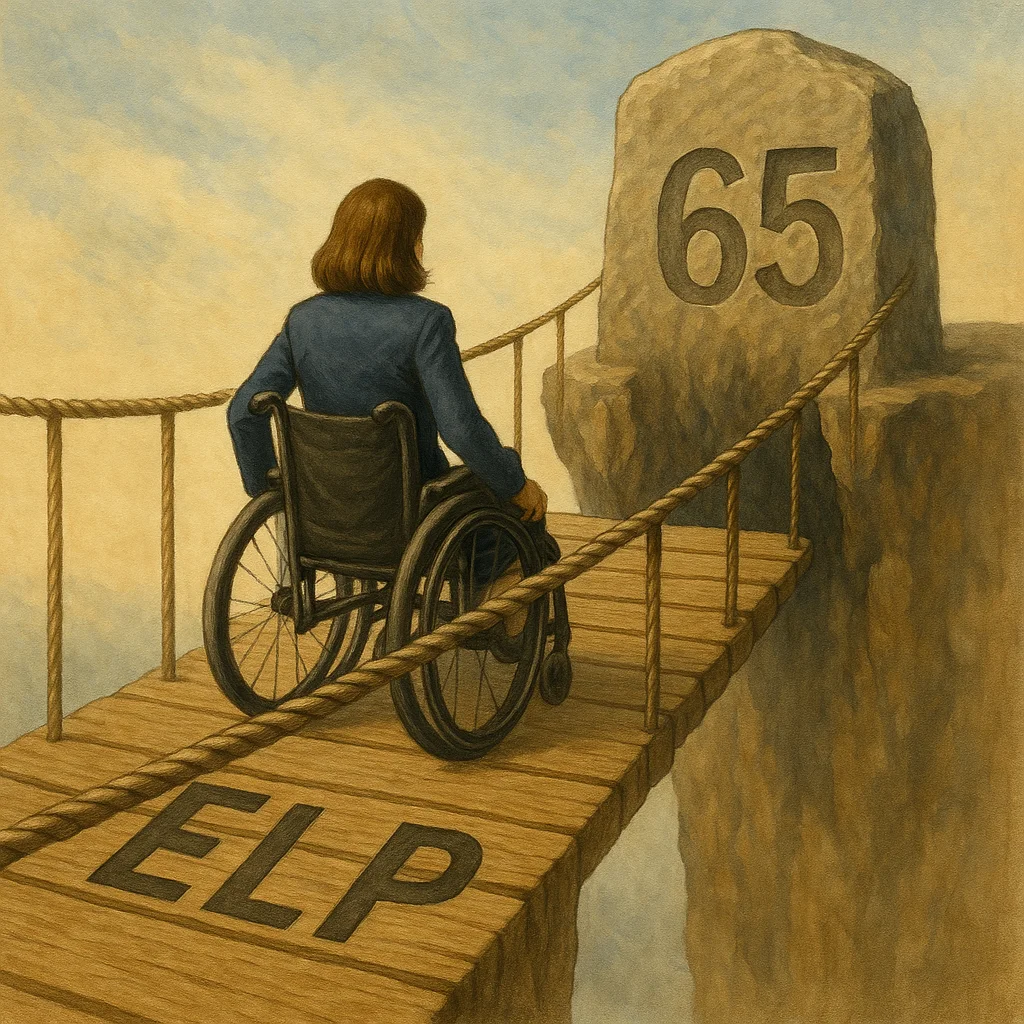
Workers who receive wage-loss benefits under WCB eventually run into the same question:
“What happens to my ELP when I turn 65?”
It’s a deceptively simple question with enormous financial consequences — and WCB does a poor job explaining the answer. Many workers assume their ELP continues for life. Others think it becomes a pension. Some believe they’ll automatically receive benefits beyond age 65 if they’re still disabled.
None of that is accurate.
This article breaks down everything you need to know about what happens to your Economic Loss Payment (ELP) at age 65, how WCB calculates your “retirement benefits,” and under what rare circumstances you can extend your ELP past the cutoff. This is written with plain-language clarity and the depth required for anyone serious about planning for their financial future after a workplace injury.
I. The Rule: ELP Always Ends at Age 65
Under WCB Alberta legislation and Policy 04-04, wage-loss compensation stops at age 65. Period.
There are no exceptions for:
Workers who are fully disabled
Workers who would have stayed in the workforce
Workers who cannot work again because of their injury
Workers who were high earners
Workers who did not save for retirement
It is one of the harshest rules in the Alberta system, and many workers only discover it late in their claim — often when they’re just a year or two away from the cutoff. WCB’s reasoning is simple (even if unfair): At age 65, they assume your loss of earnings is due to “retirement,” not injury.
Whether that was your actual intention or not doesn’t matter.
II. What You Get Instead: The Retirement Supplement
When your ELP terminates at 65, WCB replaces it with something called the Retirement Supplement.
It is not wage-loss.
It is not a pension.
It is not intended to replace your income.
Instead, WCB treats all the wage-loss benefits they’ve paid you — TTD, TPD, and ELP — as though they were “missed contributions” to your retirement savings. Their logic is that if you had worked, you would have contributed to an RRSP. Since you didn’t work, WCB pays you a hypothetical RRSP “substitute.”
Here’s how it’s calculated:
WCB takes 5% of every wage-loss dollar they paid you
They add 0.5% interest per month
That total becomes your Retirement Supplement at 65
You may receive it as a lump sum or as a monthly amount
Let’s be blunt: The Retirement Supplement is small. It does not compensate for income you lose after 65 if you’re too disabled to work.
The system is designed that way.
III. Why This Matters for Older Workers
If you’re injured at 57, 58, 60, or 62, the age-65 rule becomes critical. You might only receive a few years of ELP before WCB cuts it off. Many workers suddenly realize:
They will not be compensated for future income loss
Their CPP and OAS may be minimal
Their private RRSPs were decimated because they couldn’t work
Their cost of living is higher than expected
They may have a mortgage, car payments, or dependents at 65
Workers often say the same thing:
“I didn’t want to retire at 65. I had no plans to.”
“This injury forced me out of the workforce.”
“Why does WCB get to decide when I retire?”
The answer, unfortunately, lies in the legislation — not fairness, not medical reality, and not individual circumstances.
IV. The Exception: ELP Can Be Extended Past 65 — But Only in Rare Cases
Despite the hard cutoff, there is one narrow path to continuing ELP beyond age 65.
Policy 04-04 allows an extension only when:
There is compelling evidence you would have worked past 65, AND
Your work trajectory before the injury shows you were actively planning or preparing to do so.
These cases require strong, objective, pre-injury evidence — not after-the-fact statements.
What WCB Accepts as Evidence
WCB or the Appeals Commission may consider an extension when a worker can show:
A written contract or employer agreement confirming work beyond 65
Active business expansion in the years leading up to the injury
Recent investment in tools, equipment, or capital assets
Enrolling in trade upgrading courses or certification
Taking on major new contracts or responsibilities
A clear pattern of increasing income in the final pre-injury years
Decisions to delay CPP (e.g., planning to defer to age 70)
Evidence of long-term career plans
Strong statements from employers confirming intent to retain the worker past 65
Extensions have been granted for self-employed workers, tradespeople, and business owners whose livelihoods showed a clear upward trajectory.
What WCB Rejects
These arguments almost always fail:
“I was healthy and felt young for my age.”
“I needed the money.”
“I don’t want to retire.”
“Lots of people work past 65 these days.”
“I planned to keep going as long as I could.”
“My dad worked until he was 80.”
WCB sees these as generic statements that could be made by anyone. The bar is high because WCB assumes workers retire at 65 unless proven otherwise.
V. Why Work History Matters More Than Anything Else
The most important factor is your pre-injury work pattern.
Workers who were:
Working full-time
Working overtime
Increasing income
Expanding business operations
Taking on new responsibilities
Planning future work
Working in a vocation where the typical retirement age is >65
… have stronger extension arguments.
Workers who were:
Reducing hours
Switching to lighter duties
Semi-retired
Working seasonal or sporadic jobs
Having gaps in employment
Already on the margins at work
… face an uphill battle.
WCB is not judging character; they are judging the probability of continued earnings.
VI. Real Examples of Successful Extensions
From AC decisions across the last decade, extension approvals typically involve:
A 64-year-old electrician
Still working full time, recently renewed multiple large contracts, had no intention of retiring, had bank financing for new equipment, and told his union he planned to stay in the workforce until 70–72.
A 63-year-old self-employed tradesman
Purchased new machinery six months before the injury, had multi-year contracts lined up, and could demonstrate a rising income pattern up to the date of injury.
A 60-year-old farmer with expansion plans
Had loan documents, land purchase contracts, and equipment financing showing long-term business viability past 65.
A 62-year-old executive
Had a signed employment agreement with no retirement date and was negotiating a multi-year extension with the employer. In all examples, objective documentation carried the day.
VII. Why Extensions Are Usually Denied
Most denials cite the same reasons:
No evidence of planned work beyond 65
No business expansion
Income declining in the years before injury
Semi-retired lifestyle
Working light or modified duties
Decreased work hours
Seasonal or sporadic work
Medical history that would have shortened work-life regardless of injury
Sometimes even strong claims fail simply because the worker waited too long to gather supporting evidence. WCB does not award extensions based on sympathy. They award them based on documented, pre-injury behaviour.
VIII. What Workers Should Do If They Want an Extension
If you are:
Over 55
Have a serious claim
Are likely to receive long-term ELP
Have no plans to retire at 65
… you need to plan early.
Here’s what to gather:
1. Income records
T4s, tax returns, ROEs, business financials showing stability or growth.
2. Employer statements
Letters confirming:
Your value to the company
Their expectation of keeping you beyond 65
Your consistent full-time work
Any conversations about long-term employment
3. Proof of career investment
Trade tickets, certificates, equipment purchases, business loans, professional development.
4. CPP/OAS planning documents
Especially if you intended to defer CPP.
5. Personal statements
But only as supporting evidence, never the foundation.
Getting this together before the age-65 review dramatically increases your chances.
IX. The Retirement Supplement: What You Actually Receive at 65
Returning to the Retirement Supplement — this is the part that catches many workers off guard.
The formula:
5% of all wage-loss benefits paid
+ 0.5% interest per month
Some workers receive a few thousand. Others receive tens of thousands. But even the highest amounts still fall far short of replacing post-65 earnings.
The payout can be:
Lump sum
Monthly amount
Or a combination, depending on the option selected
Your ELP stops immediately on your 65th birthday, and the Retirement Supplement begins.
X. How This Interacts With Other Benefits
Understanding the end of ELP is also crucial for planning:
1. CPP / CPP-Disability
CPP-D ends at 65 and becomes regular CPP.
Some workers experience a sharp drop in income if ELP, CPP-D, and earnings loss end at the same time.
2. Private LTD
Many policies cut off at 65.
This creates a triple cliff: LTD stops, ELP stops, CPP-D transitions.
3. Employer pensions
If you had a pension plan but couldn’t contribute due to the injury, those lost years can hurt your retirement amount.
4. Savings / RRSPs
Many injured workers spend their RRSPs to survive during long appeals. The Retirement Supplement does not make up for this loss. Planning ahead is essential.
XI. Common Misconceptions (and the Truth)
Misconception #1:
“My ELP continues for life if I’m permanently disabled.”
No. It ends at 65.
Misconception #2:
“The Retirement Supplement is a pension.”
No. It’s a small RRSP substitute.
Misconception #3:
“If I’m still disabled at 65, WCB has to keep paying me.”
No. They do not.
Misconception #4:
“Extensions past 65 are automatic if I say I intended to keep working.”
No. They’re rare and require extensive proof.
XII. Conclusion: Know the Rules — and Prepare Early
The end of ELP at age 65 is one of the most significant turning points in any long-term WCB claim. The rules are rigid. The cutoff is firm. And the replacement benefit — the Retirement Supplement — is usually modest.
But workers who understand the rules early can:
Build evidence for a potential extension
Plan for the financial transition
Avoid surprises
Protect their long-term stability
Challenge incorrect assumptions in their file
For older workers, especially those injured in their late 50s or early 60s, a proactive strategy can be the difference between a secure retirement and a devastating drop in income.
If you’re approaching 60 and have a complex claim, this is the time to start preparing. And if you’re in your final year before turning 65, get advice now. The window to influence WCB’s decision is small — but with the right evidence and strategy, it’s not closed.